Want to see how online sales training can help teams simplify offers without sounding pushy?
Introduction of Pricing and fee increases
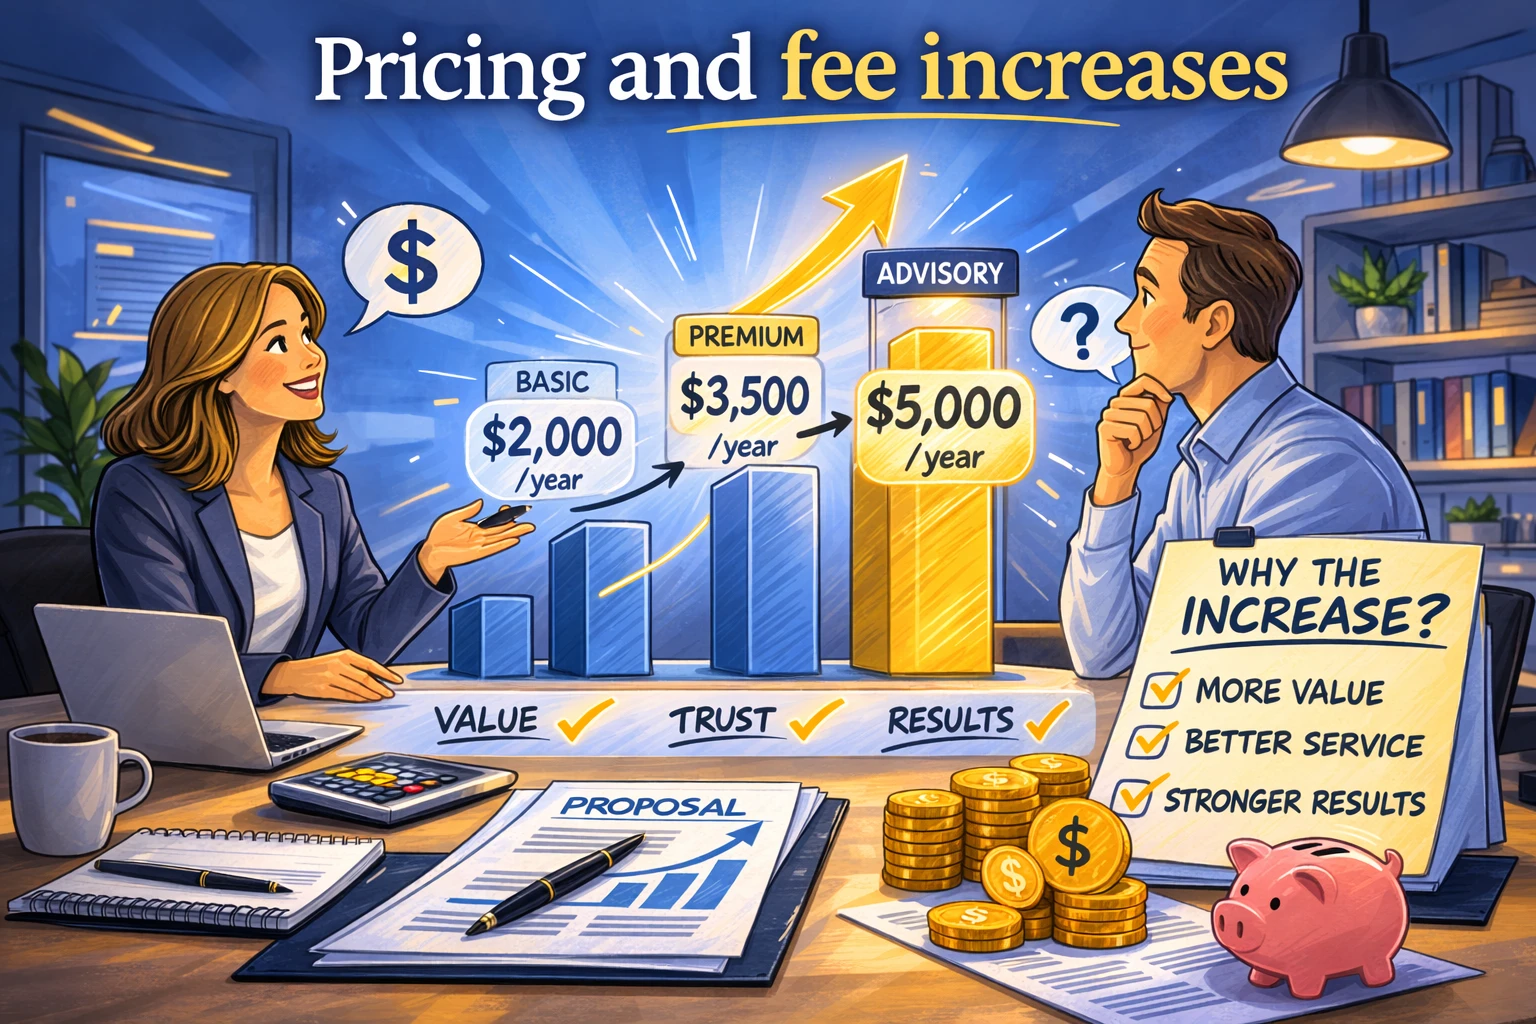
Pricing and fee increases can feel risky for a financial adviser. You know you need to charge properly. But one clumsy message can trigger doubt, complaints, or quiet exits.
Many advisers are doing more work for the same money. Extra meetings, extra calls, extra admin. The fee stays the same. And it starts to hurt margin, energy, and service quality.
Clients do not just react to the number. They react to what they think it means. This article shows you how to raise adviser fees in a way that stays fair, clear, and calm.
You will get the reasons, the prep, the wording, and the rollout steps. You will also get simple scripts for fee rises, plus what to do when you hear NO.
For financial advisers focused on retention, this is what Forbes Finance Council advisers say works best, consistent communication and clear client value, as outlined in Strategies To Boost Client Retention , and reinforced through effective sales training that strengthens long term client relationships.
The real reasons behind pricing and fee increases
Pricing and fee increases usually start with a simple truth. The service changed. The book changed. The work became heavier than the fee ever allowed.
Capacity is the silent killer here. You get more complex cases, more regulation, more planning work, and more client touchpoints. If you do not price for it, you end up cross subsidising. One client’s demand gets funded by another client’s fee.
Inflation does matter, but it is rarely the best opening line. Your costs went up sounds like a you problem. Clients care more about what stays protected, what improves, and what they can rely on.
There is also quiet unfairness. A legacy client might pay far less than a newer client for the same or bigger workload. Or you might keep low fees for a client who has grown far beyond the service they started with. So the pricing stops matching reality, on both sides.
Fix the value story before pricing and fee increases
Before pricing and fee increases, get clear on what clients believe they are paying for. Many think they pay for meetings and reports. They miss the behind the scenes work, the planning judgement, and the risk control.
Say it in plain terms. You are paid for decision support, direction, and preventing expensive mistakes. You are paid for keeping the plan on track when emotions spike and headlines shout. That is value, even when nothing “happens” on paper.
Outcomes beat activity. A client does not want ten emails. They want progress, confidence, and a plan they can stick to. Tie your service to what changes in their life and choices.
Trust also grows from consistency. Same message, same service language, same steps each year. If you sound unsure, the client will feel unsure. Clear value language makes pricing discussions feel normal, not awkward.
Choose the right type of pricing and fee increases
Pricing and fee increases do not have to be one blunt move. You can raise fees for new clients first. It lets you test the message and the market without touching existing relationships.
You can also lift minimums instead of lifting every ongoing fee. Minimums protect capacity. They also stop you taking on work that cannot be served well at the current price.
Tiers can reduce pushback because they give choice. One tier stays similar. Another adds more access, deeper planning, or more frequent reviews. Clients then pick what fits their needs and budget.
Sometimes the smartest move is to reprice one part of the service. Planning fees, ongoing fees, or implementation fees each tell a different story. A targeted price rise can feel fairer than a blanket change.
Set the number for pricing and fee increases without guessing
Pricing and fee increases should start with maths, not vibes. Work out how many clients you can serve well. Work out your time cost, overhead, and the margin you need to stay healthy.
Then price for the true time and complexity. Many advisers are not short on skill. They are short on protected time. A fee that ignores time will always create stress.
You can look at competitors, but do not copy them. Their service scope is different. Their client base is different. Their model might be less personal, or far more intensive.
Set guardrails so it stays fair. Use caps, collars, or clear bands for larger portfolios. And be honest about ethics. Charging more because you can is different from charging more because it matches real work and real responsibility.
Decide who gets pricing and fee increases first
Pricing and fee increases land best when you choose the right order. Start with clients who take the most time, have the most complexity, or sit on outdated terms. These are often lovely people, but the work no longer matches the fee.
Some clients should be protected. That might be long term relationships, vulnerable clients, or those on a limited income where the service scope is stable. Protection is not weakness. It is a choice about fairness and values.
Households need care. Couples, families, and linked accounts often feel like one relationship. If you change fees for one part and not the other, it can confuse and irritate.
Keep it consistent and easy to explain. Same rules for each group. Same service language. That is how you avoid a feeling of favouritism or random pricing.
Timing and rollout of pricing and fee increases
Pricing and fee increases need a rollout plan. Annual review cycles feel natural because clients already expect a service conversation. Anniversary dates can work too, but they are harder to manage at scale.
Notice periods matter because surprise creates fear. Thirty, sixty, or ninety days can all work. The right choice depends on your client base, your agreement terms, and how big the change is.
Choose your channel with care. Email first is efficient but can feel cold if the client is sensitive. Meeting first is warmer but can take time. A blended approach often works when the email is simple and the meeting covers questions.
Avoid a slow drip of mixed messages. One clear notice. One clear reason framed around the client. One clear next step if they want to talk it through.
Communicate pricing and fee increases without pushback
Pricing and fee increases often fail because of the opening line. Our costs went up sounds like you are passing pain across. It invites the client to question your business, not your value.
A better frame is what gets protected or improved. Clearer service scope. More proactive planning. Better access. More time for the right clients. Say what changes, and why it matters to them.
Start with one calm sentence. Then stop. Give them space to react. If you fill the air, you sound guilty.
Explain it like a menu, not a defence speech. Here is what you get. Here is what it costs. Here is when it starts. If they ask what they are getting, answer with outcomes, not tasks.
Simple scripts for pricing and fee increases
Pricing and fee increases do not need a long speech. You can use a short email that says what is changing, when, and why. Keep it direct. Invite questions without sounding like you expect trouble.
In meetings, keep it clean. State the change. Link it to service and fairness. Then ask if they want to talk through options. People often accept when it sounds normal and planned.
If someone asks for a discount, do not panic. Offer a scope choice instead. Less access, fewer meetings, or a lighter tier can keep the relationship without breaking your model.
If they compare you to another adviser, ask what they value and what they need. If they threaten to leave, stay calm and kind. A fee rise can surface fit issues that were already there.
Handle objections, NOes, and decision paralysis around pricing and fee increases
Pricing and fee increases can trigger fear of regret. Clients worry about being taken advantage of. Or they worry about changing adviser and making a mistake. The fee is just the spark.
Decision paralysis shows up as delays. They say they need to think. They stop replying. They avoid booking the next review. Treat that as emotion, not logic.
Choices reduce fear. Give two clear service options. Keep both fair. Make the difference simple to see. People find it easier to decide when the path is clear.
Avoid the give them time trap where nothing happens. Set a clear date for a follow up. Ask what they need to decide. And keep your language calm and steady.

Make operational changes that support pricing and fee increases
Pricing and fee increases must match your paperwork and your service language. Update client agreements, service descriptions, and what is included in each tier. If the docs do not match the words, trust drops.
Make sure every team member can explain the change in the same way. One wobbly message from one person can undo weeks of careful handling. Train the wording and the order of the points.
Track what happens after the change. Watch attrition, referrals, complaints, and meeting attendance. These tell you if your message is working or if something feels off.
Also track time. If your fee rises but your workload rises too, you are back where you started. Protect capacity as part of the pricing plan.
What to do if someone leaves after pricing and fee increases
Pricing and fee increases will sometimes lead to exits. Do not burn goodwill. Leave the door open. A respectful exit can still lead to referrals later.
Ask what drove the choice. Was it price. Was it value clarity. Was it cash flow. Was it a life change. You need truth, not comfort.
Learn from patterns. If many people leave in one segment, your tier might be wrong. Or your notice might be too short. Or your value story is not landing.
Then rebuild with better fit clients. A smaller book with the right pricing often gives better service, better energy, and better results.
Examples of pricing and fee increases in practice
Pricing and fee increases can work well with a new tier. Keep the current tier for those who want stability. Add a higher tier with more proactive planning and deeper review work. Make the difference obvious and simple.
Explain the change in the same way each time. Use outcomes. Use clarity. Use one clear start date. Clients accept better when it feels planned, not reactive.
Minimum increases can protect capacity fast. You raise the floor for new clients, then move legacy clients over time. It keeps your diary manageable and stops you saying yes to work you cannot serve well.
Legacy repricing can be done with respect. You can say the fee no longer matches the work and responsibility. Then offer options. Some stay. Some move tier. Some leave. And the result is a healthier business and a clearer service.
FAQ on Pricing and fee increases for financial advisers
How should financial advisers explain pricing and fee increases without sounding defensive?
Financial advisers should keep the message short and calm. Explain what is changing, when it starts, and what the client gains or keeps as a result. Link the increase to service quality, capacity, and long term support. Good sales training helps advisers say this with confidence and without over explaining. Avoid leading with business costs unless the client asks, then pause and give the client space to respond.
Should financial advisers apply pricing and fee increases to all clients or only certain groups?
Financial advisers should not treat all clients the same when making pricing and fee increases. Start with new clients and those on outdated or underpriced terms. Use clear criteria such as complexity, service demand, and time required. Sales training helps advisers set clear policies and communicate them consistently across the client bank. Consistency and a clear structure matter more than speed.
What should financial advisers do if a client refuses a pricing and fee increase?
Financial advisers should stay calm and avoid pushing back emotionally. Offer clear service options with different levels of access or support so the client can choose what fits their budget. Strong sales training prepares advisers for these conversations so they can handle objections without sounding defensive or pushy. If the client still declines, support a professional and respectful exit that protects trust and future referrals.
Nationwide Sales Training For Ambitious B2B Teams
If you’re investing in nationwide sales training, your programme should reflect your industry, buyers and commercial goals. From my base in Mansfield, I help organisations across Nottingham, London and throughout the UK, delivering practical workshops on-site or through sales training online.
Specialist programmes include financial services sales training, mortgage adviser sales training, insurance sales training, sales training for software companies, technology sales training and telecommunications sales training. I also deliver sales training for corporate teams that helps businesses simplify complex sales conversations, communicate value more effectively and convert more opportunities.
See how Master Your Pitch can help prospects understand why they should choose you.
Ready to improve your sales conversations? Book a call and let’s find the right programme for your business.

Other Useful FAQs
How do you convert more enquiries into clients?
Enquiries often stall because the process feels inconsistent or reactive. This article explains a clear structure advisers can use to turn more interest into decisions. Read converting enquiries playbook for more clients.
What marketing actually works for financial advisers?
Doing more marketing doesn’t fix an inconsistent pipeline. This article explains how advisers focus on the activities that attract the right enquiries and lead to real conversations. Read marketing for financial advisers.
What discovery meeting mistakes cost financial advisers clients?
A weak structure creates confusion early and reduces confidence before the advice is even discussed. This article explains the common discovery mistakes and how to run meetings that build trust from the start. Read discovery meeting structure mistakes advisers make.
How do financial advisers improve client retention?
Clients rarely leave because of performance alone. They leave when communication and engagement fade. This article explains how advisers keep clients confident, valued, and loyal over time. Read client retention for financial advisers.
When should financial advisers say no to small clients?
Trying to serve everyone stretches time, energy, and service quality. This article explains when to step back, how to handle the conversation, and how focusing your client base supports growth. Read saying no to small clients.
How do financial advisers position themselves as premium?
Strong advice alone doesn’t justify higher fees if your positioning feels the same as everyone else. This article explains how advisers stand out, communicate value clearly, and attract clients who expect a premium service. Read premium positioning for financial advisers.
How do financial advisers define their ideal client?
Without a clear profile, enquiries feel random and time gets wasted on poor fit conversations. This article explains how to identify your ideal client so your marketing and meetings attract the right people. Read ideal client profiling for financial advisers.
How can advice firms handle consolidation without losing clients?
Mergers and acquisitions create uncertainty that can trigger client exits. This article explains how firms communicate change, protect trust, and keep relationships stable during consolidation. Read advice firm consolidation without losing clients.
How do financial advisers improve lead funnel conversion rates?
Many firms have traffic and enquiries but too few clients. The issue is usually where prospects stall between interest and decision. This article explains how to spot the weak points and improve your lead funnel conversion. Read lead funnels and conversion rates for financial advisers.
What is the advice gap and how do advisers fix it?
The advice gap happens when prospects see your expertise but don’t feel the value enough to act. This article explains why engagement drops and how to close the gap so good prospects move forward. Read fix the advice gap for financial advisers.
How does Consumer Duty affect how advisers explain their value?
Consumer Duty raises the standard for proving value, not just stating it. This article explains how to communicate outcomes clearly so clients understand, trust the advice, and see the benefit. Read Consumer Duty and explaining value to clients.
How do advisers successfully move from commission to planning fees?
Moving to planning fees can feel risky when income has been product based. This article explains how advisers make the shift while keeping clients confident and protecting revenue. Read moving from commission to planning fees.
How can financial advisers sell without feeling pushy?
Many advisers feel resistance the moment a conversation turns toward a decision. This article explains how to guide clients forward naturally, without pressure or sales tactics. Read sales without selling for financial advisers.